Business Outlook Survey of Industrial and Service Firms - 2026
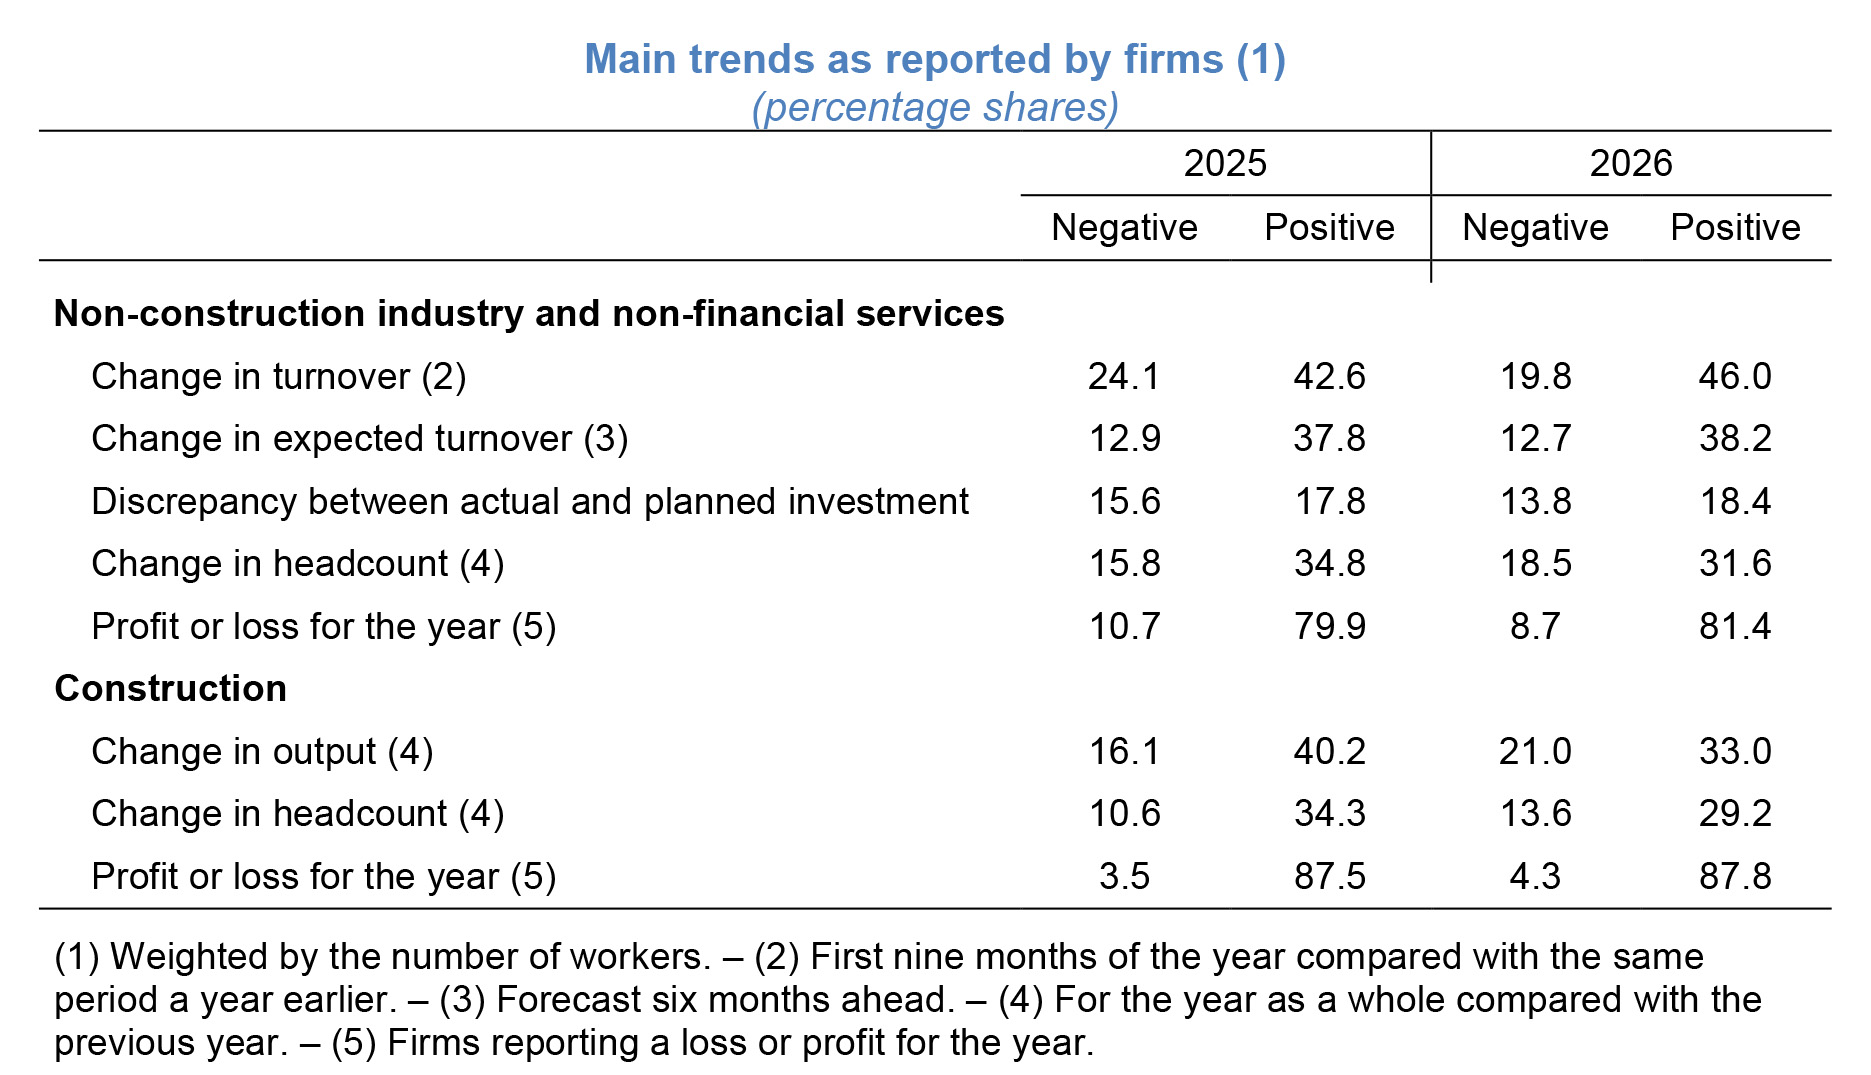
The assessments of firms with 20 or more employees point to an acceleration in sales at current prices in the first nine months of 2026, partly owing to the stronger growth in selling prices. In manufacturing, responses indicating growth have once again prevailed over reports of a contraction. The outlook for turnover remains favourable, on both the domestic and foreign markets, despite the sharp deterioration in the assessments of firms in the energy sector. Higher energy input prices have pushed up the purchasing costs of goods and services and lowered profit margins, but the vast majority of firms continue to expect to close the year with a profit.
Firms' assessments of developments in hours worked remained positive, recording an improvement in industry and remaining more favourable in services. They expect headcount employment to increase in 2026 as a whole.
Demand for bank loans remained virtually unchanged compared with the previous half-year, while the improvement in credit access conditions faded. Three out of four firms said that their liquidity was more than sufficient to cover operational needs.
Most firms confirmed the investment plans for 2026 that they had drawn up in 2025; among those that did not, upward revisions prevailed in services, while downward revisions were slightly more frequent in industry. Internal organizational factors were the main reason for revising plans. Firms expect capital accumulation to grow further in 2027.
Construction output has continued to expand in 2026, though at a significantly slower pace; the share of firms reporting a positive impact of the NRRP has declined. Expectations for 2027 point to a slowdown in output.
Report text
-
06 November 2026
-
06 November 2026TablesZIP 339 KB
-
09 November 2017
-
06 November 20262026 Business Outlook Survey: QuestionnairesZIP 350 KB

 Instagram
 YouTube
 X - Banca d'Italia
 Linkedin
 RSS
 E-mail Alert